The opinions expressed below are my own and do not necessarily represent those of Visdom Investment Group, LLC.
Bearish mix
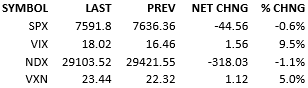
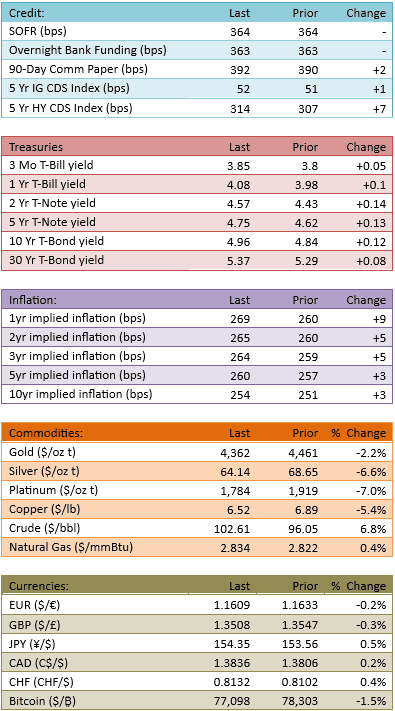
Futures were slightly positive overnight. Crude started climbing before 8 AM and futures started dropping shortly thereafter. The ECB hiked their rates 25 bips at 8:15 AM, as expected. Yields started climbing and then we saw PPI (+5.4% vs +5.3% est & +4.8% prior revised from +4.7%). Stock futures fell and bond yields climbed further. The probability of a 25 bip hike on the 16th climbed above 70%. The S&P opened down about 45 points and spent the day between down 56 and 24 points. WTI climbed throughout the session, climbing well over $100 per barrel in the afternoon. Yields climbed substantially across the curve by the end of the session. Capital flow was surprisingly light at 85%.
We wait on pins and needles for the CPI (+3.4% est vs +3.4% prior) tomorrow. However the verdict is essentially in. The Fed will likely hike on Wednesday and who knows how many more hikes are possible thereafter. The Fed won’t give guidance so markets will play the guessing game for a while. There are currently more than *three* hikes priced from now through June ’27 according to the Fed Funds futures market. That’s a hiking cycle folks. And *that* narrative still hasn’t hit the stock market.
Now we can address the crude market. It is still climbing, and substantially. WTI is up 8 consecutive sessions, about $20 per barrel in total. This runup in oil price is significant enough that we not only need to worry about inflation implications but also demand destruction. The stock market is paying close attention and without a substantial *drop* in oil prices, it is going to be very tough for stocks to trend higher.
Yields and oil are two powerful and fundamentally bearish forces altering the investing landscape for stocks right now. Notice that neither is likely to turn in the short run. These two factors are slow-moving and already have substantial momentum in the wrong direction, as far as stock market bulls should be concerned.
If we look at the chart of the S&P, bulls don’t get much help there either.
The S&P just broke below the 50-day moving average (7604). The index is down four consecutive sessions and what looked like consolidation a couple days ago, now looks like a short-term down trend. The next technical level of interest is the 100-day moving average (7491). That’s about 100 points away. Not too far but still a painful drop further.
The long-term trend for the chart is still clearly upward. The bulls have that going for them but they’ll need the dip-buyers to be heroes soon. Is that likely?
Today’s inflation data and oil price surge was a significant one-two punch for stocks. The fact that the S&P only fell about half a percent is a positive. However, I don’t like the lay of the land for the near term. Advantage bears, for a while, again.
See you tomorrow.
-Mike
Visdom Market Commentary
IMPORTANT INFORMATION
This is general educational information and market commentary and is intended for informational purposes only and is not intended as an offer or solicitation for the purchase or sale of any financial instrument or as an official confirmation of any transaction.
All market and economic data herein is as of the date hereof and sourced from Bloomberg unless otherwise stated. The information is subject to change without notice and we have no obligation to update you.
This general market commentary is intended for informational purposes only and is not intended as an offer or solicitation for the purchase or sale of any financial instrument or as an official confirmation of any transaction. The views and opinions expressed constitute the author(s) judgment based on current market conditions, are subject to change without notice, and may differ from those expressed by other employees of Visdom Investment Group LLC ("Visdom") and Visdom. Past performance and any forward-looking statements are not guarantees of future results. It is not possible to invest directly in an index.
We believe the information contained in this material to be reliable and have sought to take reasonable care in its preparation; however, we do not represent or warrant its accuracy, reliability or completeness, or accept any liability for any loss or damage (whether direct or indirect) arising out of the use of all or any part of this material. Any securities referenced are shown for illustrative purposes only, and are not intended as a recommendation or endorsement by Visdom or by the author(s) in this context. The information presented is not intended to be making value judgments on the preferred outcome of any government decision. This information does not constitute Visdom research, nor should it be considered a recommendation of a particular investment strategy or an offer or solicitation for the purchase or sale of any financial instrument. Investing involves market risk, including the possible loss of principal. You should speak to your financial advisor before making any investment decisions. Visdom and its affiliates do not provide legal, tax or account advice so you should seek professional guidance if you have questions.
