The opinions expressed below are my own and do not necessarily represent those of Visdom Investment Group, LLC.
Unanimous
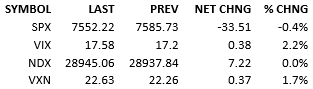
The Fed hiked rates 25 bips, as expected, and the vote was 12-0. The S&P 500 was up about 20 points at the time and only jiggled around a bit with the release of the FOMC statement. The released Dot-plot caused a bit of a stir initially too. The median rate path appears about 50 bips higher now than from the Committee’s June expectations. Perhaps this hawkish shift surprised the market but didn’t immediately affect the S&P. Later on in the session, after other major markets started to move, the S&P fell down significantly.
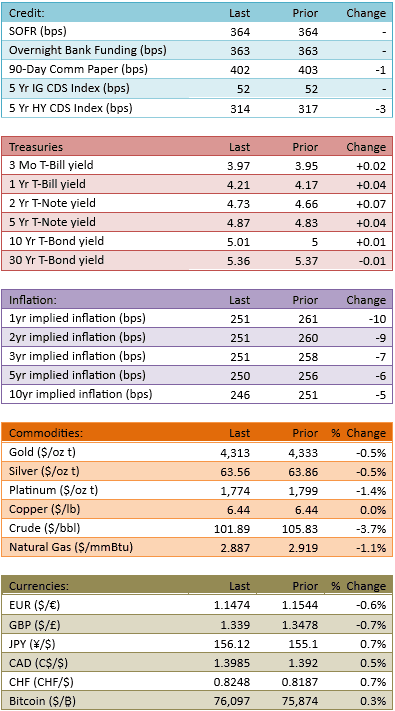
The Treasury impact was a bit more complicated. The short end yields rallied on the release of the Statement and the Dot-plot and *continued* climbing during the press conference. The long end actually dropped a bit on the release and backed up some during the presser. In a nutshell, the yield curve flattened initially but unwound that flattening through the rest of the day.
One place to look for a better market signal was actually the currency market. The Dollar strengthened immediately on the releases from the Fed and continued to strengthen during the press conference. The Dollar kept strengthening through the close. For a clear market interpretation, the FX market tells us the story. The Fed surprised *hawkishly,* even if today’s specific hike was already baked in.
One surprising detail today. The capital flow was light at 90%. Considering the significance of today’s Fed decision, I’m baffled that more capital didn’t trade. We learned a lot today and in my mind, that merits taking action in the market. Oh well. This isn’t the first time the market has me scratching my head.
Here’s the bottom line. The investing landscape just changed. The Fed is starting a *hiking cycle.* The bond market believes that the Fed will drop inflation eventually. The FX market expects a stronger Dollar. The stock market is just starting to figure out what to think.
I don’t believe the stock market fully gets it yet. We’re beginning a stretch where macro forces will be *bearish.* Throw in the fact that we’ve just broken below the 50-day moving average (7611) and we’re about to test the 100-day moving average (7511) and you’ve got a situation that’s good for the shorts and bad for the longs.
Last observation and thought. The yields on the back end of the curve climbed *significantly* shortly after the Fed statement and dot-plot released. The 2-year yield started climbing and kept climbing the whole time but the 10-year and 30-year yields dropped and then *reversed* huge. This is weird. Especially if the market thinks the Fed will bring down inflation.
So here’s my best guess: term premiums. The 2-year is 4.73% right now and it’s not farfetched to see them at 5% soon. One cannot hold 10-year and 30-year debt, even with falling inflation premiums, if the front-end compensates you that much. I do not see the back end dropping during this coming hiking cycle, *even though that’s what the Fed and the market wants.*
So what’s that going to mean to stocks? It ain’t bullish.
See you tomorrow.
-Mike
Visdom Market Commentary
IMPORTANT INFORMATION
This is general educational information and market commentary and is intended for informational purposes only and is not intended as an offer or solicitation for the purchase or sale of any financial instrument or as an official confirmation of any transaction.
All market and economic data herein is as of the date hereof and sourced from Bloomberg unless otherwise stated. The information is subject to change without notice and we have no obligation to update you.
This general market commentary is intended for informational purposes only and is not intended as an offer or solicitation for the purchase or sale of any financial instrument or as an official confirmation of any transaction. The views and opinions expressed constitute the author(s) judgment based on current market conditions, are subject to change without notice, and may differ from those expressed by other employees of Visdom Investment Group LLC ("Visdom") and Visdom. Past performance and any forward-looking statements are not guarantees of future results. It is not possible to invest directly in an index.
We believe the information contained in this material to be reliable and have sought to take reasonable care in its preparation; however, we do not represent or warrant its accuracy, reliability or completeness, or accept any liability for any loss or damage (whether direct or indirect) arising out of the use of all or any part of this material. Any securities referenced are shown for illustrative purposes only, and are not intended as a recommendation or endorsement by Visdom or by the author(s) in this context. The information presented is not intended to be making value judgments on the preferred outcome of any government decision. This information does not constitute Visdom research, nor should it be considered a recommendation of a particular investment strategy or an offer or solicitation for the purchase or sale of any financial instrument. Investing involves market risk, including the possible loss of principal. You should speak to your financial advisor before making any investment decisions. Visdom and its affiliates do not provide legal, tax or account advice so you should seek professional guidance if you have questions.
