The opinions expressed below are my own and do not necessarily represent those of Visdom Investment Group, LLC.
Questions.
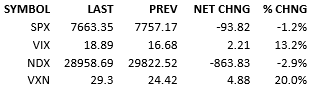
Shareholders did not like what they learned from Meta and Tesla. Whether it was their capital spending plans, or their debt situation, or something else, is debatable and various news stories covered those topics among others. The bottom line is that risk-off was the name of the game, beginning overseas. Our market opened down about 70 points and was down over 100 by 10:30 AM. TSLA and META have huge weightings in the S&P 500 and they directly pushed the index lower. They also spurred risk-off behavior in other AI-themed stocks. Yields fell 13-17 bips across the curve, a huge move, in a significant flight-to-safety reaction. Bonds reacted to stocks today, an unusual, but not unheard of situation. Capital flow was significant, 126%.
Risk-off and risk-on days are part of the investing experience. It is not surprising that we would experience a risk-off day, instigated by the mega cap tech. These stocks can only upside surprise for so long. It was only a matter of time. Today is the time. So rather than pick through the minutia of what details soured which investors, we should be asking a bigger question.
Is this the beginning of a bearish trend?
Obviously, we do not know. However, we should take a look around and see if there’s a mosaic we can piece together.
Earnings season
Earnings were supposed to be the driver, and justifier, of the bull market. The non-mega cap tech stocks did not inspire the overall market. The two of the first three reporting mega cap tech stocks did not inspire the overall market.
Interest rates
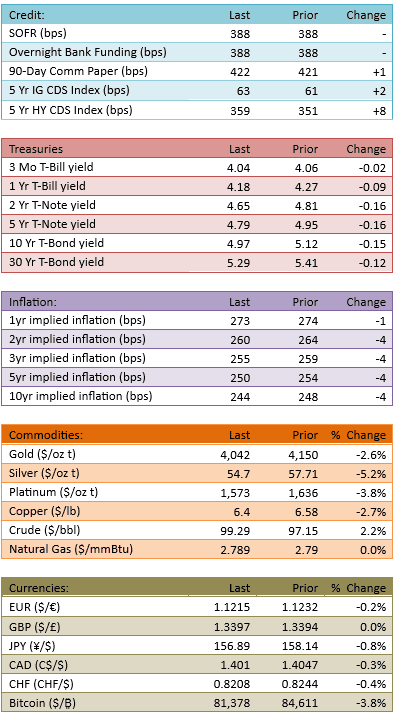
The Fed is at the start of a hiking cycle. Yields in the market are down substantially in October. The curve is essentially back at mid-September levels.
Credit
Issuance by both sovereign and corporate issuers is climbing significantly and credit metrics are showing cause for concern. CDX Markit credit default indices for both investment grade and high yield debt are substantially above their mid-summer levels. They are near the levels of late March, at the height of worry after the start of the US/Iran conflict.
Crude
Crude too, is approaching levels seen in late March. Mid-summer crude dipped as low as $70 per barrel for a while. Now we are bumping up on $100.
Economy / Labor
The economy continues to grow signficantly, although the real rate is modest. Recent housing suggests that market is feeling the pressures of elevated rates. Unemployment remains historically low and weekly jobless numbers are not only low but also quite stable.
Inflation
The most recent CPI was 3.7%, well north of the Fed’s 2% target. After bouncing around 2.5% for much of 2025, it surged above 3% in March, as had stubbornly remained there. The most recent CPI print was an uptick from the prior month, which surprised the market considerably.
An investing conclusion is not obvious from what I’ve summarized above. If you can tell me how all of the above will behave going forward, we could make a confident equity market prediction. Of course we can’t.
However, what happens if all of the above stay about where they currently are? Do we think that inspires the equity bulls or bears?
What needs to happen for all of the above to shift in bullish ways for the stock market?
How likely are those positive shifts versus negative ones?
When I look at the major factors that matter to stocks, I see the negative risks outweighing the positive ones. Things can certainly change in an instant but for that change to be *positive* for stocks, it would take a very large surprise, no?
See you tomorrow.
-Mike
Visdom Market Commentary
IMPORTANT INFORMATION
This is general educational information and market commentary and is intended for informational purposes only and is not intended as an offer or solicitation for the purchase or sale of any financial instrument or as an official confirmation of any transaction.
All market and economic data herein is as of the date hereof and sourced from Bloomberg unless otherwise stated. The information is subject to change without notice and we have no obligation to update you.
This general market commentary is intended for informational purposes only and is not intended as an offer or solicitation for the purchase or sale of any financial instrument or as an official confirmation of any transaction. The views and opinions expressed constitute the author(s) judgment based on current market conditions, are subject to change without notice, and may differ from those expressed by other employees of Visdom Investment Group LLC ("Visdom") and Visdom. Past performance and any forward-looking statements are not guarantees of future results. It is not possible to invest directly in an index.
We believe the information contained in this material to be reliable and have sought to take reasonable care in its preparation; however, we do not represent or warrant its accuracy, reliability or completeness, or accept any liability for any loss or damage (whether direct or indirect) arising out of the use of all or any part of this material. Any securities referenced are shown for illustrative purposes only, and are not intended as a recommendation or endorsement by Visdom or by the author(s) in this context. The information presented is not intended to be making value judgments on the preferred outcome of any government decision. This information does not constitute Visdom research, nor should it be considered a recommendation of a particular investment strategy or an offer or solicitation for the purchase or sale of any financial instrument. Investing involves market risk, including the possible loss of principal. You should speak to your financial advisor before making any investment decisions. Visdom and its affiliates do not provide legal, tax or account advice so you should seek professional guidance if you have questions.
