The opinions expressed below are my own and do not necessarily represent those of Visdom Investment Group, LLC.
Old habits?
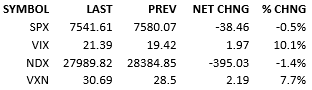
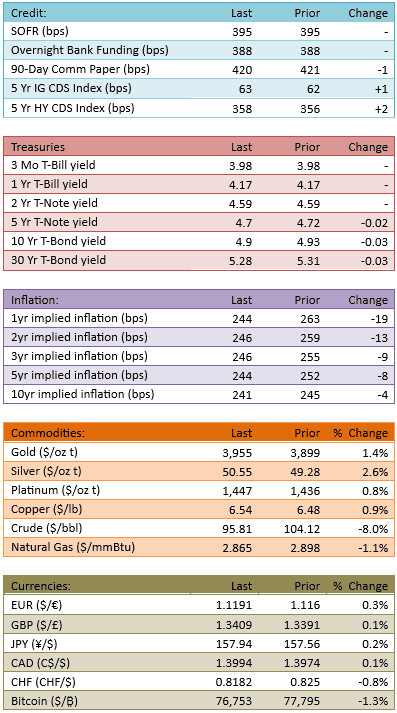
News wasn’t very consequential today but headlines out of Iran and the White House suggested possible diplomatic paths forward and crude reflected that hope. WTI was off about $3 last night and only dropped further as time passed, and the drop ended up being quite large. S&P futures traded about +35 in the premarket and the index rallied after the open to +80. The intraday top was around 10:30 AM and, at that moment, it looked like the dip-buyers were at work and in charge. Tech was leading. Prices began to drop from that point on though. There’s no clear news or data to explain it. As the index fell, it was tech leading the way. The index went negative in the afternoon and finished with at modest loss. The intraday turn was significant even if the close looks unremarkable.
Without a clear cause to today’s turn, we struggle with what investors might be sensitive to. What might worry investors further? What might turn sentiment back to bullish? Considering the importance of tech, Apple and Palantir’s earnings announcements tonight are very significant. That would be true no matter how today’s tape behaved though.
Oil always matters too. The huge drop *should* have inspired more bullishness in the stock market but perhaps stock investors are still concerned about a post mid-terms resumption of military actions?
The big picture isn’t very different today, than Friday. The dip-buyers showed up, probably inspired by crude, but they couldn’t hold on to their gains. I don’t read into that *too* much but I wouldn’t ignore it either.
Perhaps this market is just going to trade heavy for a while.
See you tomorrow.
-Mike
Visdom Market Commentary
IMPORTANT INFORMATION
This is general educational information and market commentary and is intended for informational purposes only and is not intended as an offer or solicitation for the purchase or sale of any financial instrument or as an official confirmation of any transaction.
All market and economic data herein is as of the date hereof and sourced from Bloomberg unless otherwise stated. The information is subject to change without notice and we have no obligation to update you.
This general market commentary is intended for informational purposes only and is not intended as an offer or solicitation for the purchase or sale of any financial instrument or as an official confirmation of any transaction. The views and opinions expressed constitute the author(s) judgment based on current market conditions, are subject to change without notice, and may differ from those expressed by other employees of Visdom Investment Group LLC ("Visdom") and Visdom. Past performance and any forward-looking statements are not guarantees of future results. It is not possible to invest directly in an index.
We believe the information contained in this material to be reliable and have sought to take reasonable care in its preparation; however, we do not represent or warrant its accuracy, reliability or completeness, or accept any liability for any loss or damage (whether direct or indirect) arising out of the use of all or any part of this material. Any securities referenced are shown for illustrative purposes only, and are not intended as a recommendation or endorsement by Visdom or by the author(s) in this context. The information presented is not intended to be making value judgments on the preferred outcome of any government decision. This information does not constitute Visdom research, nor should it be considered a recommendation of a particular investment strategy or an offer or solicitation for the purchase or sale of any financial instrument. Investing involves market risk, including the possible loss of principal. You should speak to your financial advisor before making any investment decisions. Visdom and its affiliates do not provide legal, tax or account advice so you should seek professional guidance if you have questions.
