The opinions expressed below are my own and do not necessarily represent those of Visdom Investment Group, LLC.
Labor data for Labor Day
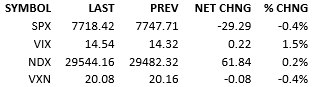
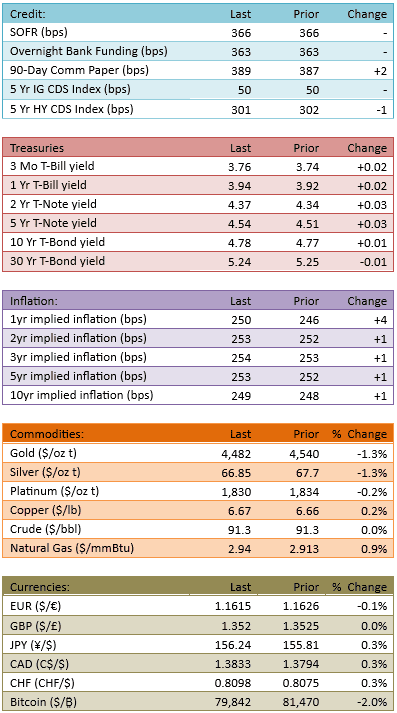
Nonfarm payrolls (+162k vs +55k est & +21k prior revised from -23k) were hotter than expected. Revisions added a lot of jobs to prior months too. The narrative of a weak job market was immediately undone and reversed. The data says we have a healthy job market. Bonds sold off, FOMC hiking probabilities rose, equity futures sold, the Dollar strengthened. All these market reactions are typical for a hot jobs surprise. The S&P opened down small but leaked value through the morning. The Index finished down modestly. Despite the material nonfarm payrolls data, capital flow remains at summer levels, 80%.
The economy is not as weak as was thought and the labor market is not struggling. This means that the Fed doesn’t have to worry too greatly about derailing the economy should it hike rates. In their balancing act, they must weigh the health of the labor market against the risks of inflation. Based on today’s data, the Fed can focus almost exclusively on addressing inflation. If the committee feels that inflation isn’t dropping quickly enough, hiking rates will be an easy vote.
This leaves us laser-focused on the coming inflation data. PPI (+5.2% est vs +4.7% prior) releases next Thursday and CPI (+3.4% est vs +3.4% prior) releases next Friday.
According to the Warsh speech from Jackson Hole, and even the supposedly dovish comments from Governor Waller yesterday, those inflation numbers have to show *cooling.* Forget the estimates, that’s for the market. For the Fed, the numbers have to show *sequential* drops. That means *at least* 4.6% for PPI and 3.3% for CPI.
It’s going to take quite a data surprise for those inflation results to print.
The stock market pulled back on its rates-will-stay-put optimism today but I think they’ve got to abandon their wishful thinking. We must wait to see the numbers but it is much more likely that the inflation data won’t come down *fast enough* to keep the Fed off the brake.
We’ve got a 3-day weekend ahead. US markets open on Tuesday. We will likely trade gently until the inflation data prints. At that point, the path of the Fed should be pretty clear and the markets will react accordingly.
See you Tuesday, have a great holiday weekend.
-Mike
Visdom Market Commentary
IMPORTANT INFORMATION
This is general educational information and market commentary and is intended for informational purposes only and is not intended as an offer or solicitation for the purchase or sale of any financial instrument or as an official confirmation of any transaction.
All market and economic data herein is as of the date hereof and sourced from Bloomberg unless otherwise stated. The information is subject to change without notice and we have no obligation to update you.
This general market commentary is intended for informational purposes only and is not intended as an offer or solicitation for the purchase or sale of any financial instrument or as an official confirmation of any transaction. The views and opinions expressed constitute the author(s) judgment based on current market conditions, are subject to change without notice, and may differ from those expressed by other employees of Visdom Investment Group LLC ("Visdom") and Visdom. Past performance and any forward-looking statements are not guarantees of future results. It is not possible to invest directly in an index.
We believe the information contained in this material to be reliable and have sought to take reasonable care in its preparation; however, we do not represent or warrant its accuracy, reliability or completeness, or accept any liability for any loss or damage (whether direct or indirect) arising out of the use of all or any part of this material. Any securities referenced are shown for illustrative purposes only, and are not intended as a recommendation or endorsement by Visdom or by the author(s) in this context. The information presented is not intended to be making value judgments on the preferred outcome of any government decision. This information does not constitute Visdom research, nor should it be considered a recommendation of a particular investment strategy or an offer or solicitation for the purchase or sale of any financial instrument. Investing involves market risk, including the possible loss of principal. You should speak to your financial advisor before making any investment decisions. Visdom and its affiliates do not provide legal, tax or account advice so you should seek professional guidance if you have questions.
