The opinions expressed below are my own and do not necessarily represent those of Visdom Investment Group, LLC.
Summer’s over
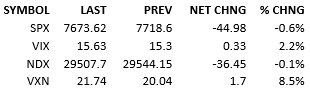
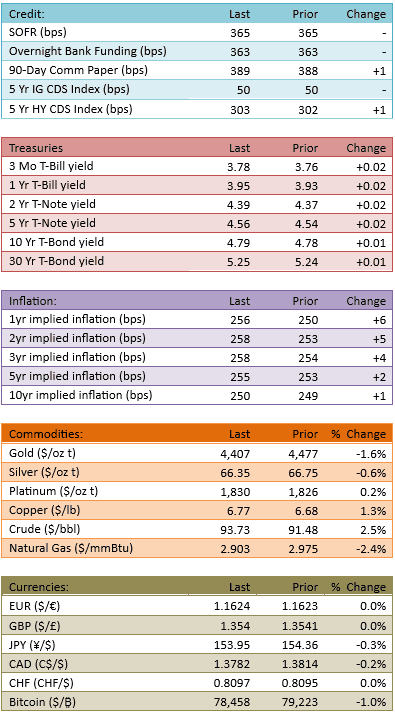
Attacks on Iranian tankers moved the crude market higher and Treasury yields climbed as well, whether in sympathy or coincidently is unclear. Both those markets pressured stocks lower and the S&P opened down about 10 points. The index quickly fell in initial trading and spent the bulk of the day in the down 30 to 40 point range. Despite the unofficial end of summer trading, capital flow remains light, hitting 90% today.
Inflation and the September decision from the Fed are front-and-center issues for the market. The next PPI (+5.3% est vs +4.7% prior) and CPI (+3.4% est vs +3.4% prior) data release Thursday and Friday respectively. Current Fed hike probabilities are 60%. There’s a lot riding on those data so perhaps the lack of capital flow today is explained by investors waiting.
From a charting standpoint, the bulls’ brief advantage is gone and short-term trading is likely rangebound. The S&P remains in the consolidation range from early August. An important downside level is 7598 and an important upside one is 7817. Without a catalyst, we will likely stay within these levels. Inflation data seems to be the catalyst around the corner and it should kick the index strongly to test one of them and give us some technical direction.
If the news can be relatively tame for a day or so, Thursday morning’s PPI should be the moment of truth.
See you tomorrow.
-Mike
Visdom Market Commentary
IMPORTANT INFORMATION
This is general educational information and market commentary and is intended for informational purposes only and is not intended as an offer or solicitation for the purchase or sale of any financial instrument or as an official confirmation of any transaction.
All market and economic data herein is as of the date hereof and sourced from Bloomberg unless otherwise stated. The information is subject to change without notice and we have no obligation to update you.
This general market commentary is intended for informational purposes only and is not intended as an offer or solicitation for the purchase or sale of any financial instrument or as an official confirmation of any transaction. The views and opinions expressed constitute the author(s) judgment based on current market conditions, are subject to change without notice, and may differ from those expressed by other employees of Visdom Investment Group LLC ("Visdom") and Visdom. Past performance and any forward-looking statements are not guarantees of future results. It is not possible to invest directly in an index.
We believe the information contained in this material to be reliable and have sought to take reasonable care in its preparation; however, we do not represent or warrant its accuracy, reliability or completeness, or accept any liability for any loss or damage (whether direct or indirect) arising out of the use of all or any part of this material. Any securities referenced are shown for illustrative purposes only, and are not intended as a recommendation or endorsement by Visdom or by the author(s) in this context. The information presented is not intended to be making value judgments on the preferred outcome of any government decision. This information does not constitute Visdom research, nor should it be considered a recommendation of a particular investment strategy or an offer or solicitation for the purchase or sale of any financial instrument. Investing involves market risk, including the possible loss of principal. You should speak to your financial advisor before making any investment decisions. Visdom and its affiliates do not provide legal, tax or account advice so you should seek professional guidance if you have questions.
